 Trading Desk
Basel: A Setback as a New Opportunity
-
Christian Ingerl
Redaktor
Following the strong rally since the half-year results, Basilea’s stock has pulled back. However, an upward revision to the full-year forecast and promising Phase III projects point to further upside potential. A new trading opportunity is opening up for risk-tolerant investors.
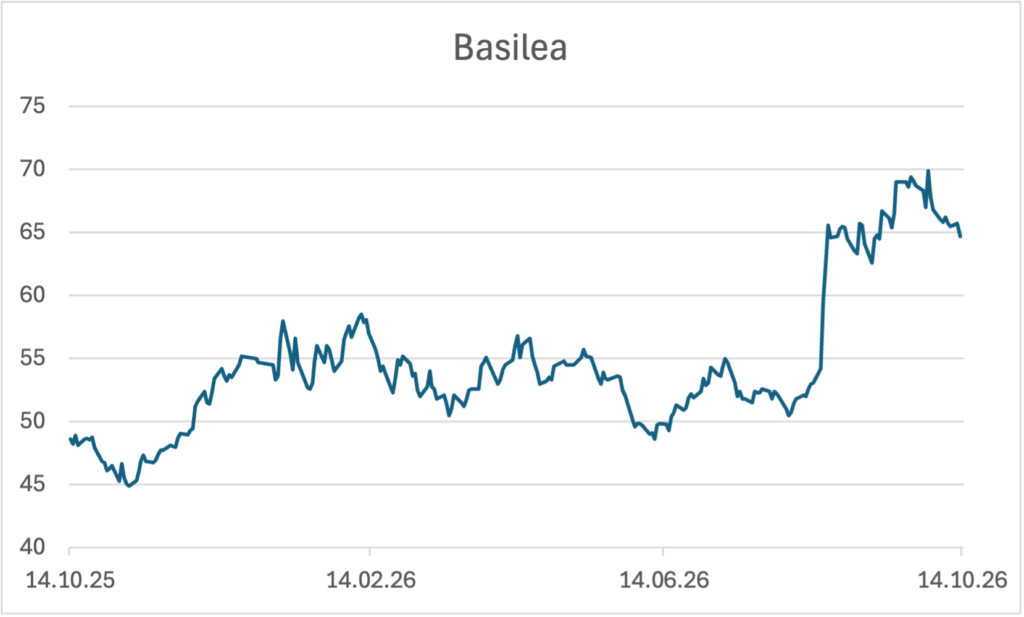
The rally in the stock price of Basilea has now entered a period of consolidation. Since the release of the strong half-year report and the simultaneous upward revision of the full-year forecast, the stock had gained significant momentum, peaking at CHF 70.50. From there, it has recently fallen by about 7%. Given the previous rally, this is not an cause for alarm at this point. On the contrary: a former resistance zone lies around CHF 65, which could now act as support following the breakout. If the stock manages to find a bottom here, the broader uptrend could continue.
A disproportionately large increase in profits…
Not only do technical indicators point to a sustained positive trend, but fundamental factors also support this view. The first half of the year, in particular, provides ample cause for optimism. Basilea increased revenue by 14% compared with the same period last year, to CHF 119.0 million. Profitability showed even stronger growth: Operating profit climbed by nearly a third to CHF 31.6 million, while net income rose by about three-quarters. The two drugs, Cresemba and Zevtera, generated revenues of CHF 92.3 million. Basilea is not skimping on the future: Research and development expenditures increased from CHF 38.3 million to 54.0 million. The funds are primarily being directed toward the Phase III programs for the antifungal drug Fosmanogepix, as well as the preparation for the Phase III development of ceftibuten-ledaborbactam.
…leads to higher goals
This strong performance prompted management to raise its forecast. Instead of revenue growth of about one-tenth, Basilea now expects growth of about 15% for 2026. The bar was raised particularly significantly for operating profit: After previously announcing 20%, the increase is now expected to be around 40%. Revenues from Cresemba and Zevtera are expected to total approximately CHF 210 million, while cash flow from commercial operations is projected to rise to around CHF 180 million.
However, investors aren’t just looking at the current year; another key factor is how well Basilea manages the transition from Cresemba to its next growth drivers. Fosmanogepix is considered the most important long-term value driver in this regard.
The next generation of products is on the horizon
Cresemba is currently the company’s financial powerhouse. Between July 2025 and June 2026, the antifungal drug generated global in-market sales of USD 817 million—a 25% increase—and is now marketed in 76 countries. But Basilea is already building the next generation. The company estimates the peak sales potential for Fosmanogepix at around USD 1 billion and for Ceftibuten-Ledaborbactam at about USD 500 million.
Basilea aims to have four commercial products in its portfolio by 2030. The existing products, Cresemba and Zevtera, are intended to finance this transition: The company expects cumulative cash flow of approximately CHF 600 million from both drugs between 2026 and 2030, along with more than USD 350 million in potential additional research funding.
However, looking to the future is not entirely without risk. Cresemba remains the company’s most important revenue driver for the time being, so a faster-than-expected decline in revenue following patent expirations would hit Basilea hard. Similarly, clinical setbacks with Fosmanogepix or slower market penetration by Zevtera could undermine the investment thesis. Investors should mark October 28 on their calendars, as that is when the next Capital Markets Day will take place, during which new developments may be announced.
Investment Solution
If Basilea stock holds steady around CHF 65, the recent pullback could present a new trading opportunity. Speculative investors can capitalize on this scenario with Leonteq’s long mini-future MBSBST. The product has a leverage of 4.4. But be careful: While the multiplier ensures that price movements in the stock are amplified in the product, this works in both directions. The strike price is CHF 50.2765, and the stop-loss level is 51.7848 francs—currently a good fifth below the underlying’s price.