 Trading Desk
SoftwareOne: Unfairly Punished?
-
Christian Ingerl
Redaktor
Sometimes exceeding expectations isn’t enough: Although the IT service provider outperformed forecasts in the third quarter and even raised its annual targets, its stock price plummeted. The negative reaction may be overdone and could present a rebound opportunity for bold investors.
At first glance, there’s little to criticize. SoftwareOne increased revenue in the third quarter by just under one-tenth to CHF 377.3 million, exceeding analysts’ estimates of around CHF 371 million. Earnings were even more encouraging: Adjusted EBITDA climbed 21.8% to CHF 79.5 million, also exceeding the consensus estimate of CHF 77.5 million. The operating margin improved from 19.0% to 21.1%.
The software and cloud services business was once again the key growth driver. As a result, the Services division posted an 11.2 percent increase in revenue. Consulting services related to AI, cloud infrastructures, and cybersecurity were in particularly high demand. The transition from Microsoft’s traditional Enterprise Agreements to the Cloud Solution Provider (CSP) model is also opening up additional business opportunities. This enables SoftwareOne not only to provide customers with software licenses but also to support them over the long term in optimizing their IT landscape.
However, the picture within the group is mixed. While the direct business returned to growth with a 2.9% increase following a weak previous quarter, the channel business lost significant momentum. After growth rates of more than 30% in the first half of the year, the increase most recently amounted to just 7.3%. Regionally, the Asia-Pacific region and Central and Eastern Europe performed particularly well. In the DACH region, however, business virtually stagnated.
Higher Margins, New Opportunities
Nevertheless, management believes it is on track. For 2026, SoftwareOne continues to forecast currency-adjusted revenue growth in the mid- to high-single-digit percentage range. At the same time, the forecast for the adjusted EBITDA margin has been raised from over 23% to more than 24%. A boost is coming from the integration of the Norwegian competitor Crayon, whose acquisition was completed in the summer of 2025. The measures already implemented are enabling annual cost savings of around CHF 100 million, with an additional 5 to 10 million expected by the end of the year.
The long-term outlook also remains attractive. The increasing shift of software applications to the cloud, as well as the widespread adoption of artificial intelligence, are driving up demand for consulting services among companies. SoftwareOne aims to capitalize on this trend through its combined licensing and services business. By 2030, the Group aims to achieve average annual revenue growth in the high single-digit percentage range and an EBITDA margin of more than 28%.
Doubts Lead to Setbacks
The fact that the stock market nevertheless reacted with skepticism is primarily due to the expected slowdown in growth. Some market participants fear that revenue growth in the final quarter—and possibly also in the first half of 2027—could fall below 5%. However, these concerns may be exaggerated, as the underlying business momentum remains fully intact. Analysts at Kepler Cheuvreux, for example, expect growth to accelerate again starting in the second half of 2027. The experts therefore view the valuation—at 13.5 times expected earnings for 2027—as significantly lower than that of many competitors, which are trading at multiples between 15 and 20. However, a higher valuation remains contingent on the integration efforts proving sustainable and growth picking up again.
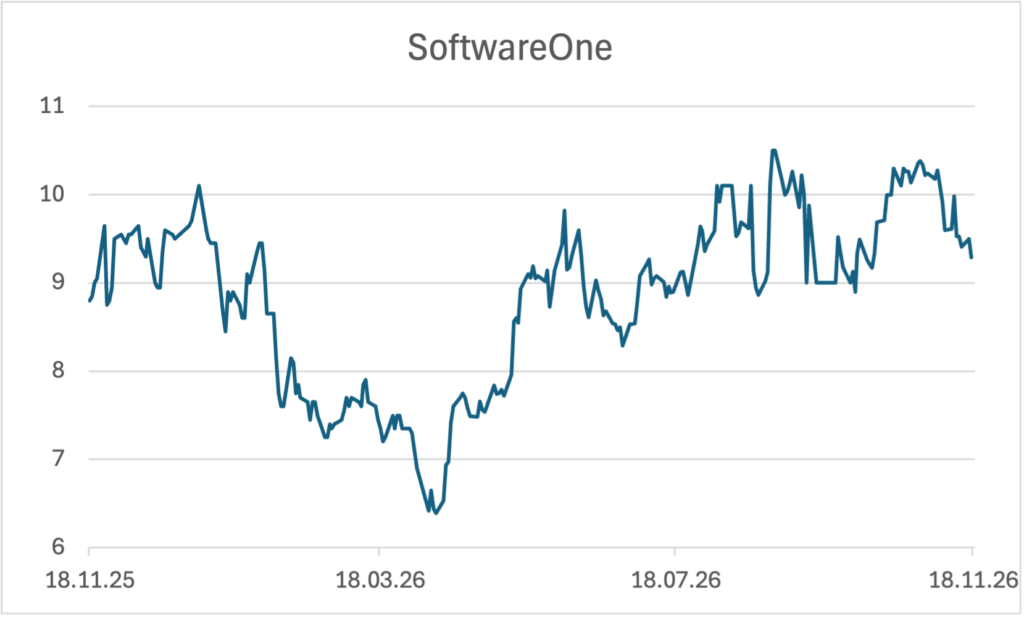
From a technical analysis perspective, SoftwareOne is at an interesting turning point. Since hitting its annual high in August, the stock has lost about 15% and has recently fallen below the 100-day moving average. The stock is now encountering a horizontal support zone around CHF 8.50. Just below that, the 200-day moving average provides additional support. If the stock manages to find a bottom here, a return to double-digit prices could be on the horizon. A break below both support levels, however, would significantly cloud the technical outlook.
Solutions for a possible turnaround…
Speculative investors can use two long mini-futures to bet on a recovery with varying degrees of aggressiveness. The more conservative of the two leverage options comes from Zürcher Kantonalbank ISWJIZ. The product has a leverage of 4.45, and the stop-loss threshold is CHF 6.92—about one-fifth below the current stock price.
Leonteq’s long mini-future is significantly more bullish MSWB2T is positioned much more aggressively. Its leverage is 9.1. With a barrier at CHF 7.85, the risk buffer is only about one-tenth. In return, the product reacts much more strongly to price movements in the underlying asset.
…or other divers
In the event of further price declines, however, a short UBS Mini Future is a good option SEBHXU. The product has a leverage of 3.9, and the stop-loss threshold is CHF 10.39—about 19% above the current price. If SoftwareOne falls below the support zone at CHF 8.50 and the 200-day moving average just below it, the downward trend could accelerate. Investors holding the short product would benefit disproportionately from such a move.