 Interviews
Gold Mirrors the Fed
-

Susan Niederhöfer
Chefredakteurin
Amid political pressure on the US Federal Reserve, a 27% plunge in silver over just two days and the approaching US midterm elections, 2026 has been a year of extremes for investors in precious metals. The discussion explores the driving forces behind the heightened volatility, the role of central banks and the decision that matters most for investors in precious metals right now.
Mr Schirm, the US midterms are approaching. Which factors are already influencing the market – the balance of power, fiscal policy or simply uncertainty?
It is not the election result itself that is affecting the market, but the resulting fiscal arithmetic. The decisive variable is the composition of Congress and what it means for the development of the deficit, the issuance volume of the Treasuries and the term premium included in long maturities. The equity rally, which historically begins around 22 trading days before election day, is real but secondary; it is a consequence of the clarity on the fiscal outlook, not an independent driving force. The current constellation makes this particularly easy to read. The yield on the 30-year US Treasuries stands at 5.30%, a 19-year high.
For an investor whose coupons are priced at the long end of the US curve, the election is therefore a duration event, not an equity event. The key question is not which party wins the House of Representatives, but whether the new balance of power comes up with a credible path to deficit reduction or whether it simply means a different form of fiscal expansion.
In January, gold stood at around USD 5,600; today it is trading at approximately a fifth lower. The trigger was not an economic data point but a personnel issue. What does it say about gold when a single name moves the price by 20%?
Gold was priced on the basis of an idiosyncratic political position rather than a macroeconomic equilibrium. In other words, a 20% price decline following a single personnel decision shows that the premium rested on a specific expectation of institutional erosion as well as on a concrete dollar debasement narrative.
When gold and silver fell on 30 January 2026 in light of the likely appointment of Kevin Warsh, the market was pricing in the impact on the future path of monetary policy. This happened in the context of his long-standing criticism of ultra-expansive monetary policy. It reveals something that is of a structural and by no means of an incidental nature. It tells us three things:
The January peak was a premium for the optionality of monetary policy. A gold price of USD 5,595 implied a world in which the Fed remains supportive or even eases. However, when this optionality was repriced within a single trading day, the precious metal promptly gave back the premium.
The exit is narrower than the entrance. A move of this magnitude on the back of a single announcement implies that positioning was very crowded and that the pool of rational buyers had already been exhausted. The subsequent slump in silver, which fell from USD 116.70 to USD 85.20 within two days, suggests that leverage was one of the amplifiers.
Gold is increasingly becoming a shadow asset for the Fed. In a world in which the communication function of the Fed is unstable, gold not only sets a price on inflation but also on the credibility of the institution. This represents a qualitatively different risk factor compared with previous cycles.
After the crash, your bank wrote that the rally had contained a premium for expected political influence over the Fed. Is that not an elegant way of saying gold was too expensive?
The answer is a crystal-clear “yes and no”. At USD 5,595, gold was expensive relative to the interest rate environment that followed. Both trading volumes and turnover rates had risen significantly. “Too expensive”, however, is only half the answer. For our clients, the more useful observation is that gold is now trading at a level at which the premium for the credibility of monetary policy has been left behind, leaving only the fiscal and de-dollarisation premiums.
While overvaluation is a static statement about the price relative to the fair value, a premium for political influence is a statement about the composition of the price and the conditions under which it diminishes. This distinction is crucial. If gold was simply overvalued, the answer would be to reduce the position. If, however, the gold price contained a premium for the expected subordination of the Fed, one would have to assess whether the institutional safeguards (Fed independence, the confirmation process and legal precedent) are genuinely undergoing a seismic shift or merely need to be reinterpreted by the market. The recovery in August suggests that the market is still debating this rather than declaring the thesis void.
The Fed is not cutting, it is tightening. From a textbook perspective, that is detrimental for a non-yielding asset. Yet, August was the third-strongest month for gold in the last 25 years. What is overriding the interest rate effect: central bank demand, fiscal risk or simply the search for an alternative to the dollar?
All three, but in a specific order. Central bank demand forms the structural floor: it is price-insensitive, policy-driven and tenacious enough to absorb the entire supply. Fiscal risk provides the narrative bridge. With US gross debt of more than USD 40 trillion and interest costs exceeding the defence budget, the argument that rates are high but the currency is fragile is popular. The search for an alternative to the dollar provides the cyclical tailwind that amplifies the other two factors when confidence in the US central bank weakens. What unites them is that none of them depends on the level of interest rates in isolation; rather, all of them depend on confidence in the issuer of the currency in which those rates are denominated.
The performance in August, the third-strongest month for gold in 25 years, is consistent with this framework: the ETF GLD recorded inflows of USD 5.03 billion in August alone, the largest monthly inflow of 2026, followed by a further USD 2.1 billion in September. This is not a momentum of the retail market but an institutional reallocation into gold as a fiscal hedge at a time when the Fed is tightening rather than easing.
The BIS ascribes the silver crash in January to leveraged retail products, ETF premiums and margin increases. To what extent did investor sentiment and product mechanics contribute to the precious metals boom in 2025?
The silver data of 2026 provide the definitive answer. Silver peaked at USD 116.70 on 28 January and fell to USD 85.20 by 30 January, a slump of 27% in two days. By mid-July, it had fallen to USD 55.52, a decline of 52% from its January peak. It is currently trading at USD 65.83, down 8.1% since the start of the year. According to the Shanghai Futures Exchange (SHFE), the sheer trading volumes and transaction frequency were a good indicator of the exuberance and the subsequent hangover.
Leveraged retail products, ETF premiums and margin increases describe the mechanics of the change, but not the cause of the original movement. The cause was sentiment, that is, the view that silver, both as a monetary metal and as an industrial input for the energy transition, was structurally undervalued relative to gold. This view resulted in leveraged positioning via Structured Products and ETFs, creating a self-reinforcing premium over the spot price.
Once the appointment of Kevin Warsh had led to a repricing of the monetary policy outlook, the ETF premium collapsed, margin calls were triggered and the leveraged retail layer was liquidated simultaneously. The BIS is right in its view that product mechanics amplified the crash. But without the preceding sentiment-driven surge in the investor base, the crash would not have been possible.
With precious metals, the distinction between “fundamental value” and “product-included premium” is not merely academic. An ETF trading at a premium to its net asset value (NAV) in a momentum environment does not represent a metal position but a sentiment position with metal as the underlying. Position sizing and liquidity conditions must take this distinction into account.
For Swiss investors, an unhedged gold position also entails exposure to the US dollar. While gold is slightly up in USD, the picture in CHF is considerably weaker. How do you address this with clients, and what has changed over the past three years?
For a long time, the debate centred on the costs of hedging versus the benefits. Most of the time, the answer was to hedge, as the assumption was that the US dollar would weaken and the Swiss franc would strengthen. Today, however, the framework has reversed. With USD/CHF at around 0.8165 and a Swiss franc that has tended to weaken rather than strengthen in 2026, the unhedged dollar exposure in a gold position contributes positively to the return in CHF. Nevertheless, the same investor who would not hedge a US equity allocation hesitates to leave a gold position unhedged. This is because gold is perceived as a safe haven in Swiss franc terms, which creates a behavioural preference for currency neutrality.
More than ever, the first question has to be: what do you want to hedge? The metal, the currency or your accounting base? If the ans-wer is “accounting base”, a quanto structure can be justified despite its cost. If the answer is “metal”, the dollar exposure is part of the strategy and not a risk that needs to be eliminated.
Quanto or no quanto: with an interest rate differential of around 3.75 percentage points between the Fed and the SNB, hedging takes a noticeable bite out of the coupon. At the same time, the negative correlation between gold and the US dollar is an argument in favour of hedging. Which effect dominates in the current regime?
The hedging costs prevail, because the correlation argument has changed in the current regime. With an interest rate differential of around 3.75 percentage points, the annual cost of a CHF quanto on a USD gold position eats up a large part of the realistic coupon or carry income. The negative correlation between gold and the US dollar would normally be an argument in favour of a hedge: a rising US dollar weighs on the gold price in USD, while the currency hedge stabilises the CHF return. However, this correlation is currently unstable. Gold has risen slightly in USD and fallen significantly in CHF, breaking the familiar inverse pattern.
In a regime in which the correlation is unreliable, it is hard to justify paying 3.75 percentage points to hedge a relationship that is not behaving as expected. The pragmatic approach is to size the position in such a way that the unhedged CHF volatility is tolerable, rather than paying the full quanto premium in order to eliminate it.
Although precious metals have topped the performance rankings for two years, commodities account for only around 3% of underlyings on the Swiss market, according to the Swiss Structured Products Association (SSPA). Is the industry failing here, or is it the investor?
Neither applies in isolation; the constraint is of a structural nature. Swiss institutional investors, pension funds in particular, operate under passive mandates. Matching liabilities denominated in Swiss francs with corresponding assets is a regulatory and actuarial necessity, not a matter of preference. A 3% allocation to commodities may seem low compared with current performance rankings, but it is consistent with a system in which liabilities and reporting currency are in CHF and the regulatory framework prioritises the certainty of nominal returns over the benefits of diversification. The investor is not being irrational in holding a small allocation, and the industry is not failing in providing access.
If there is a shortcoming, it lies in communication: performance rankings invite backward-looking allocation decisions, while the structural case for precious metals (fiscal hedging and currency differentiation) requires a forward-looking, multi-year conviction for which annual review cycles are poorly suited.
If investors could make only one decision in precious metals today, what would it be?
In the current market environment, position size is likely to matter more to investors than currency hedging. The most serious mistake today is paying 3.75 percentage points for a quanto hedge on a gold position in CHF when the dynamics between the US dollar and the Swiss franc do not deliver the corresponding correlation. The second most serious mistake is holding an unhedged position at full target weight when the interest rate environment is tightening and the premium component is questionable.
The solution is to hold a smaller, unhedged position: large enough to preserve the fiscal hedge and the diversification rationale, and small enough that losses in CHF do not force an exit at the worst possible moment. This is not an assessment of whether the gold price will rise or fall, but an assessment of how to survive in the regime in which gold is trading.
Thank you very much for this insightful conversation, Mr Schirm.
__
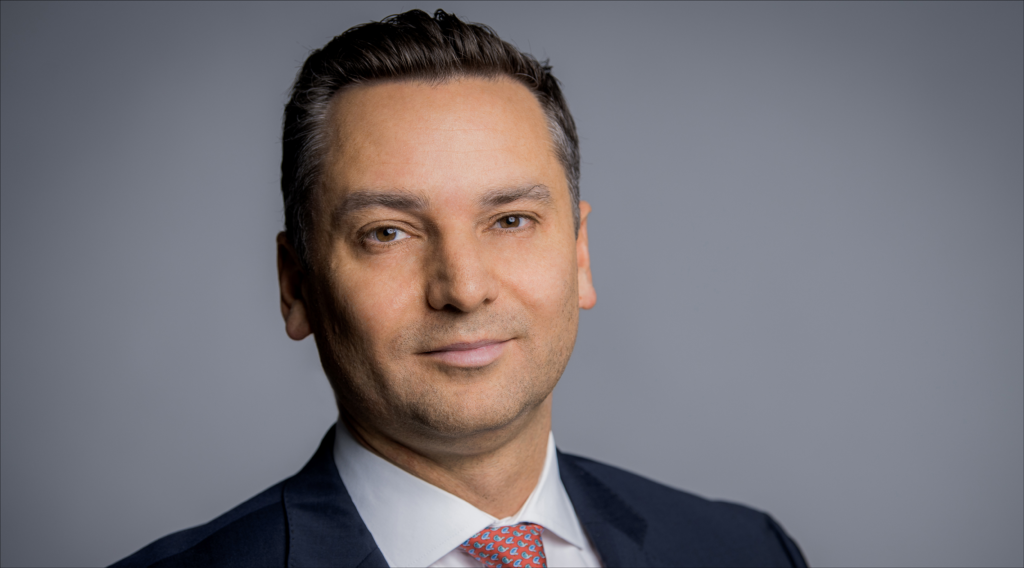
Jonas Schirm
Executive Director, Head FX/PM Institutional Sales, Bank Julius Baer
Jonas Schirm is an experienced professional in the financial services industry. With 20 years of experience at institutions such as Dresdner Kleinwort, Commerzbank, CLS and Credit Suisse in Frankfurt, New York, London and Zurich, he has deepened his expertise across various functions. In January 2024, he joined Bank Julius Baer in Zurich as Head of Foreign Exchange/Precious Metals (FX/PM) Institutional Sales, focusing on the global development of institutional FX/PM offering and strengthening the competitive position of Bank Julius Baer for ultra-high-net-worth (UHNW) and family office clients. He holds a variety of banking qualifications and a Master in Global Finance and Banking.