 Trading Desk
Helvetia Baloise: Ready to Conquer the Summit
-
Christian Ingerl
Redaktor
The group has posted a strong first half-year as a combined entity and is making faster progress on integration than planned. This is also giving the stock a boost, bringing the record high back within reach. Depending on market expectations, investors have two paths to success.
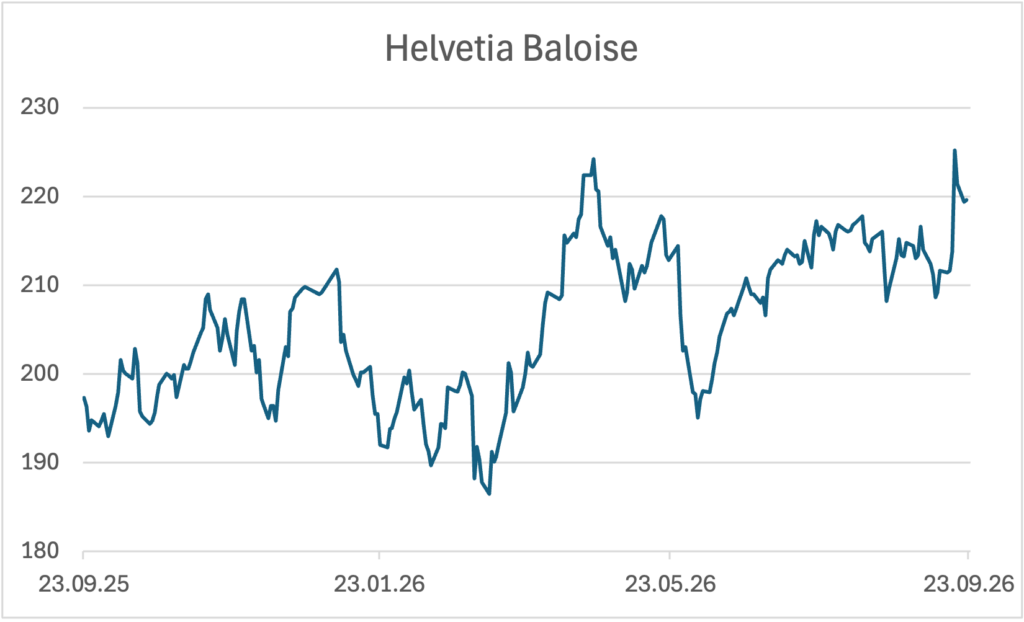
At Helvetia Baloise, things aren’t just going well in the insurance business right now. On the stock market, too, the group—formed from the merger of Helvetia and Baloise—has recently shifted into high gear. Following the release of its first combined half-year results, the stock temporarily jumped by more than 5%. The stock is now trading again very close to its previous record high of CHF 222.60. The latest figures certainly provide reasons to believe that the climb to new heights may not be over yet.
The first joint half-year financial results are impressive. Helvetia Baloise reported underlying earnings of CHF 631.6 million, exceeding consensus estimates by 9%. The annualized adjusted return on equity reached 18.7%, exceeding even the target range of 16% to 18% set for 2026 through 2028. By contrast, the reported IFRS net income of just CHF 84.6 million appears sobering at first glance. However, this is primarily due to accelerated amortization of merger-related intangible assets. This accounting effect has no impact on the company’s ability to pay dividends.
Property and Casualty Impressive
The non-life business delivered a particularly strong performance. With a business volume of CHF 7.13 billion, it contributed underlying earnings of CHF 399.4 million. The combined ratio stood at a solid 92.0%. Even more importantly, the underlying claims ratio for the current year was significantly better than the market had expected. This suggests that the results are driven not only by investment income but also by improvements in the core insurance business. In the life business, while business volume fell short of expectations, this was partly intentional: Helvetia Baloise is shifting its business toward capital-efficient products and semi-autonomous retirement solutions.
Merger Pays Off Sooner Than Expected
The real highlight of the figures, however, lies in the integration. Of the long-term annual synergies and efficiency gains of CHF 650 million, nearly half had already been achieved or secured on a run-rate basis as of the end of June. Management has raised its forecast for the end of the year from around 50% to about 60%. At the same time, total integration costs are expected to remain in the lower half of the originally stated range of CHF 500 to 600 million. The contribution to earnings from synergies is now expected to reach approximately CHF 170 million in 2026—CHF 20 million more than previously anticipated. And provided there are no further major losses, the Group maintains its forecast of 10% to 12% growth in underlying earnings per share for the current fiscal year.
Also noteworthy were the comments regarding operational integration. According to management, price increases continue to outpace inflation, while so far there has been neither a noticeable rise in customer churn nor a decline in customer satisfaction as a result of the merger. The merger is now entering its second phase, with a focus on system migration, IT consolidation, and the continued realization of synergies. Artificial intelligence is already playing a practical role in this process. The AI assistant “Clara” handles more than 250,000 customer interactions annually.
Investment Opportunities
On the stock market, the string of strong earnings reports has sparked renewed optimism and brought the previous high of CHF 222.60 back into play. If the price breaks out above this level, it could signal a new buying opportunity from a technical analysis perspective. Bullish investors can position themselves for this with the long mini-future IHBWLZ from ZKB. The product has a leverage of 5.1. The stop-loss level is at CHF 182.7054, which represents a 17.7% margin to the knock-out threshold.
On the other hand, those looking for a high-yield breather will find the Callable Barrier Reverse Convertible SBXLJB from Julius Bär a sideways-trending alternative. The maximum yield is 7.13% or 6.38% per year. The barrier is set at CHF 161.55, which is a good 27% below the current stock price. For investors who expect a consolidation phase following the recent rally, this buffer is a decisive factor.